The first half of 2026 was really a tale of two quarters for diversified real assets.
KEY TAKEAWAYS
- Real assets delivered strong gains year to date, despite a pause in Q2 as market optimism shifted back toward AI-related equities.
- Secular trends remain intact as demand for essential physical assets have increased, as AI, energy demand and resource constraints, as well as a repriced real estate market, continue to support growth.
- Valuations remain attractive, supporting the long-term case for real assets and the diversification, income and long-term return potential the asset class may offer.
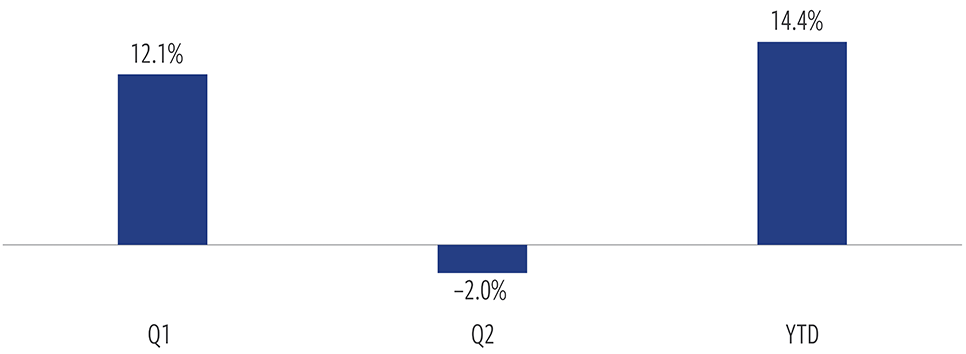
Diversified real assets gained 12.1% in the first quarter as investors became concerned about narrow market leadership, rising geopolitical tensions and the potential for higher inflation.
Capital flowed toward businesses tied to the physical economy, including real estate, infrastructure and natural resource equities.
In the second quarter, tensions in the Middle East eased.
Inflation expectations moved lower and enthusiasm returned to AI-related equities.
Diversified real assets declined 2% during the quarter.
Real assets strong returns paused in Q2 before resuming in second half
At July 31, 2026. Source: Bloomberg
Geopolitical tensions re-emerged to start the second half of the year, reminding investors of the risks that drove first-quarter performance.
We don’t expect a return to the peak levels of stress and uncertainty seen earlier this year, but recent developments reinforce our view that supply security, energy resilience and inflation- sensitive assets remain important.
With the strong start to the third quarter included, diversified real assets were up 14.4% year to date through July, outperforming a traditional 60/40 portfolio by more than eight percentage points in that period.
All real asset sleeves posted strong returns through July.
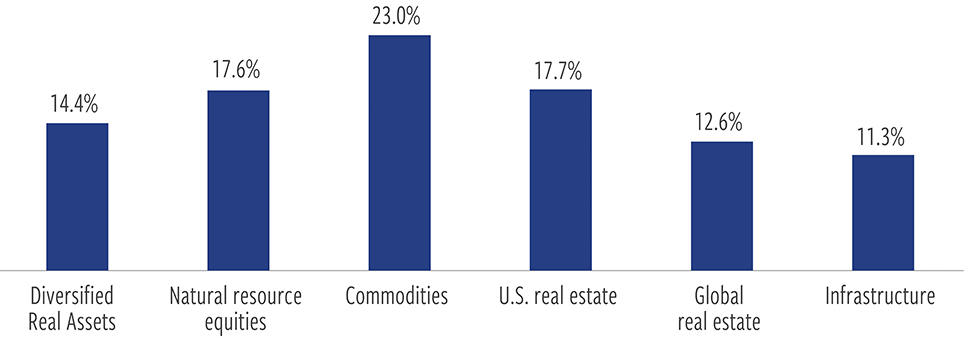
All real assets sleeves have performed strongly
At July 31, 2026. Source: Bloomberg
Natural resources equities returned 17.6%, Commodities 23.0%, U.S. listed real estate returned 17.7%, global listed real estate returned 12.6%, global listed infrastructure gained 11.3%.
The key point is that while investor sentiment has shifted, the underlying investment story did not.
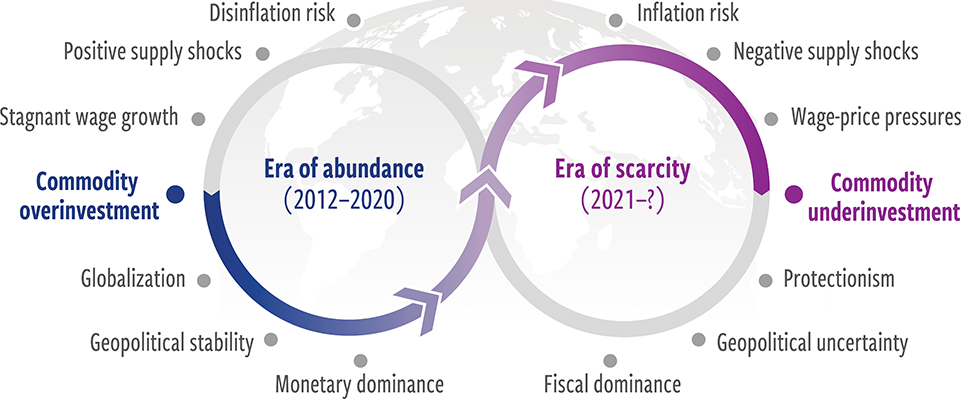
Our central investment thesis remains what we call the Era of Scarcity.
At June 30, 2026. Source: Cohen & Steers.
For much of the decade prior to the pandemic, abundant capital, inexpensive energy, efficient supply chains and a generally stable geopolitical backdrop benefited investors.
In the years since, inflation risk, supply shocks, geopolitical uncertainty and protectionism have risen.
Demand for essential physical assets has increased, while supply constraints have climbed. We see this dynamic across energy markets, infrastructure, real estate and critical resources.
Artificial intelligence has not only created heavy market concentration in broader equities, it’s also driving expected growth in data intensity—posing opportunities for energy, critical materials and infrastructure.
And it’s one of several secular themes driving growth and strong fundamentals across real assets.
These are: Data demand, Deglobalization, changing demographics, decarbonation, and resource scarcity, which I mentioned earlier.
We also believe investors may be overlooking the fact that real estate prices have largely reset, while fundamentals have continued to improve driven by limited supply and a resilient global economy.
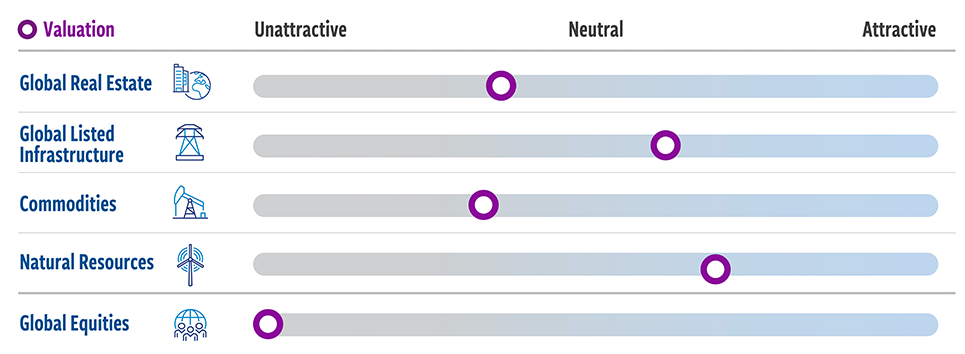
The final piece of the investment case is valuation.
While the broader equities trade at generally elevated valuations, real assets remain significantly more attractive than global equities.
Core real asset valuations remain significantly more attractive than global equities
At June 30, 2026. Source: Bloomberg, S&P Xpressfeed and Cohen & Steers.
Valuations: reflects the z-score of a proprietary set of valuation metrics, specific to each asset class.
So while markets may continue to move between enthusiasm for AI and concerns about inflation, geopolitics or economic growth, our view remains unchanged.
We believe investors are increasingly recognizing the value of owning scarce, tangible assets with inflation sensitivity whose value is supported by powerful long-term demand drivers.
Real assets continue to offer an attractive combination of diversification, inflation resilience, income generation and long-term return potential.
And we believe that opportunity remains compelling as we look ahead to the second half of the year.
ABOUT THE AUTHORS
Fabrizio Palmucci, Vice President, is a member of Cohen & Steers’ Portfolio Specialist Group
Data quoted represents past performance, which is no guarantee of future results. An investor cannot invest directly in an index and index performance does not reflect the deduction of any fees, expenses or taxes. Index comparisons have limitations as volatility and other characteristics may differ from a particular investment.
The views and opinions presented are as of the date of publication and are subject to change. There is no guarantee that any market forecast set forth in this document will be realized. This material represents an assessment of the market environment at a specific point in time and should not be relied upon as investment advice, does not constitute a recommendation to buy or sell a security or other investment and is not intended to predict or depict performance of any investment.
This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or to account for the specific objectives or circumstances of any investor. We consider the information to be accurate, but we do not
represent that it is complete or should be relied upon as the sole source of appropriateness for investment. Cohen & Steers does not provide investment, tax or legal advice. Please consult with your investment, tax or legal professional regarding your individual circumstances prior to investing.
Index definitions
U.S. REITs: FTSE Nareit All Equity REITs Index.
Global REITs: FTSE EPRA Nareit Developed Real Estate Index.
Infrastructure: FTSE Global Core 50/50 Net Tax Index
Natural resource equities: S&P Global Natural Resources Index (Net)
Commodities: Bloomberg Commodity Total Return Index.
60/40 stock/bond allocation: 60% MSCI World Index and 40% ICE BofA US Treasury 7-10 Year Bond Index.
Real assets blend: 27.5% real estate, 27.5% commodities, 15% natural resource equities, 15% infrastructure, 10% short-duration fixed income and 5% gold.
Short-duration fixed income represented by ICE BofA 13 Year U.S. Corporate Index.
Gold represented by the gold spot price in U.S. dollars per troy ounce.
The real assets blend is not representative of an actual portfolio and is for illustrative purposes only.
Risks of investing: Investing involves risk, including entire loss of capital invested. There can be no assurance that the investment strategy will meet its investment objectives. Diversification is not guaranteed to ensure a profit or protect against loss. A real assets
strategy is subject to the risk that its asset allocations may not achieve the desired risk return characteristic, underperform other similar investment strategies or cause an investor to lose money. Risks of investing in REITs are similar to those associated with direct investments in real estate securities, including (i) property values may fall due to increasing vacancies, declining rents resulting from economic, legal, tax, political or technological developments, lack of liquidity, limited diversification and sensitivity to certain economic factors such as interest rate changes and market recessions. The value of commodity-linked derivative instruments may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. The use of derivatives presents risks different from, and possibly greater than, the risks associated with investing directly in traditional securities, including market risk, credit risk, counterparty risk, leverage risk and liquidity risk and can lead to losses because of adverse movements in the price or value of the underlying asset, index or rate, which may be magnified by certain features of the derivatives. Securities of natural resource companies may be affected by events occurring in nature, inflationary pressures and international politics. Global infrastructure securities may be subject to regulation by various governmental authorities, such as rates charged to customers, operational or other mishaps, tariffs and changes in tax laws, regulatory policies and accounting standards. Foreign securities involve special risks, including currency fluctuation and lower liquidity.
Futures Trading Is Volatile, Highly Leveraged and May Be Illiquid. Investments in commodity futures contracts and options on commodity futures contracts have a high degree of price variability and are subject to rapid and substantial price changes. Such investments could incur significant losses. The use of options on commodity futures contracts is to enhance risk-adjusted total returns. The use of options, however, may not provide any, or only partial, protection for market declines. The return performance of the commodity futures contracts may not parallel the performance of the commodities or indexes that serve as the basis for the options it buys or sells; this basis risk may reduce overall returns.
Cohen & Steers Capital Management, Inc. (Cohen & Steers) is a U.S. registered investment advisory firm that provides investment management services to corporate retirement, public and union retirement plans, U.S. endowments, foundations and mutual funds. Cohen & Steers Asia Limited is authorized and regulated by the Securities and Futures Commission of Hong Kong (ALZ367). Cohen & Steers Japan Limited is a registered financial instruments operator (investment advisory and agency business and discretionary investment
management business with the Financial Services Agency of Japan and the Kanto Local Finance Bureau No. 3157) and is a member of the Japan Investment Advisers Association. Cohen & Steers Ireland Limited is regulated by the Central Bank of Ireland
(No.C188319). Cohen & Steers UK Limited is authorized and regulated by the Financial Conduct Authority (FRN458459). Cohen & Steers Singapore Private Limited is a private company limited by shares in the Republic of Singapore.
For Investors in the Middle East: This is for information purposes only. It does not constitute or form part of any marketing initiative, any offer to issue or sell, or any solicitation of any offer to subscribe or purchase, any products, strategies or other services nor shall it or the fact of its distribution form the basis of, or be relied on in connection with, any contract resulting therefrom. In the event that the recipient wishes to receive further information with regard to any products, strategies other services, it shall specifically request the same in writing from us.