
A changing market regime is prompting investors to reconsider traditional portfolio assumptions. Real assets can expand the toolkit, but effective implementation depends on clear investor objectives and an understanding of the tradeoffs involved.
KEY TAKEAWAYS
- The market regime has changed.
A world defined by stickier inflation, tighter supply conditions, higher rates and geopolitical uncertainty may require a broader portfolio toolkit. - Real assets can help address multiple portfolio needs.
Because their value is tied to tangible assets, essential demand, scarcity and often inflation-linked cash flows, real assets may support diversification, inflation resilience, income and long- term growth. - Implementation should begin with the investor’s objective.
Each real asset category offers something different to a portfolio, and the right allocation depends on the investor’s goals and whether they prefer to build, buy or blend allocations.
For much of the decade following the global financial crisis, investors benefited from an era of abundance. Low inflation, declining interest rates, globalization and ample liquidity supported strong equity returns, while bonds provided effective diversification. For many investors, the traditional 60/40 portfolio worked exceptionally well.
Today’s environment looks markedly different.
Markets have demonstrated resilience in 2026, but several structural forces are reshaping the investment landscape. Geopolitical tensions, supply chain realignment, growing power demand, and years of underinvestment in critical infrastructure and resource production have contributed to a less certain inflation outlook, new secular growth drivers, and rising investor interest in the so-called “HALO” trade (hard assets, low obsolescence).
EXHIBIT 1
Investors may need a different toolkit for a world defined by tighter supply and greater uncertainty
Many of the assumptions that shaped portfolios over the past decade are being challenged
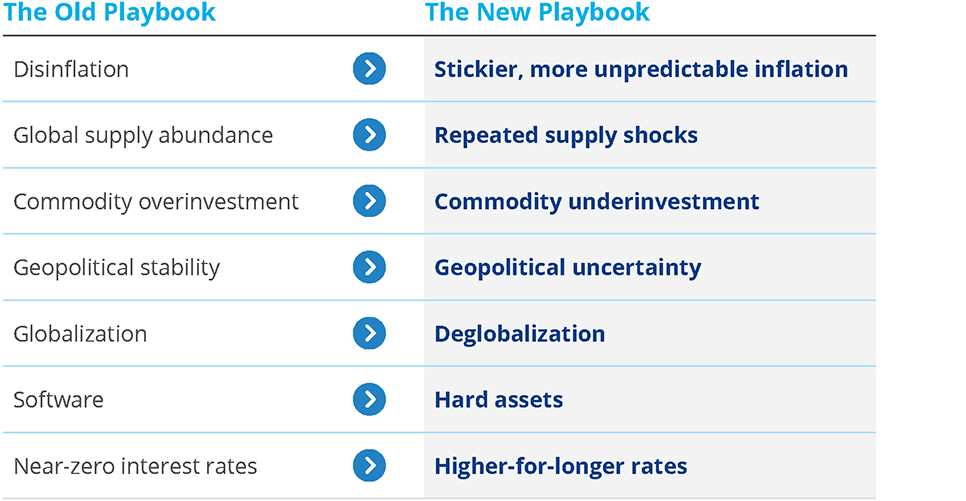
This shift matters because inflation can weaken the diversification investors have historically received from stocks and bonds. When inflation is elevated or unpredictable, stock/bond correlations may become less reliable, challenging traditional portfolio construction.
At the same time, new secular themes have created growth drivers ranging from AI-related data demand to deglobalization and demographic change, accelerating the buildout of essential assets. Meanwhile, years of underinvestment have led to higher commodity prices, as scarcity is meeting increasing demand.
Equity markets are also highly concentrated, leaving many portfolios increasingly dependent on a narrow group of companies and sectors. Meanwhile, stock/ bond correlations are high, meaning the traditional balance that bonds provide in moments of market volatility may not be dependable (Exhibit 2).
EXHIBIT 2
The diversifying properties of real assets are increasingly important today
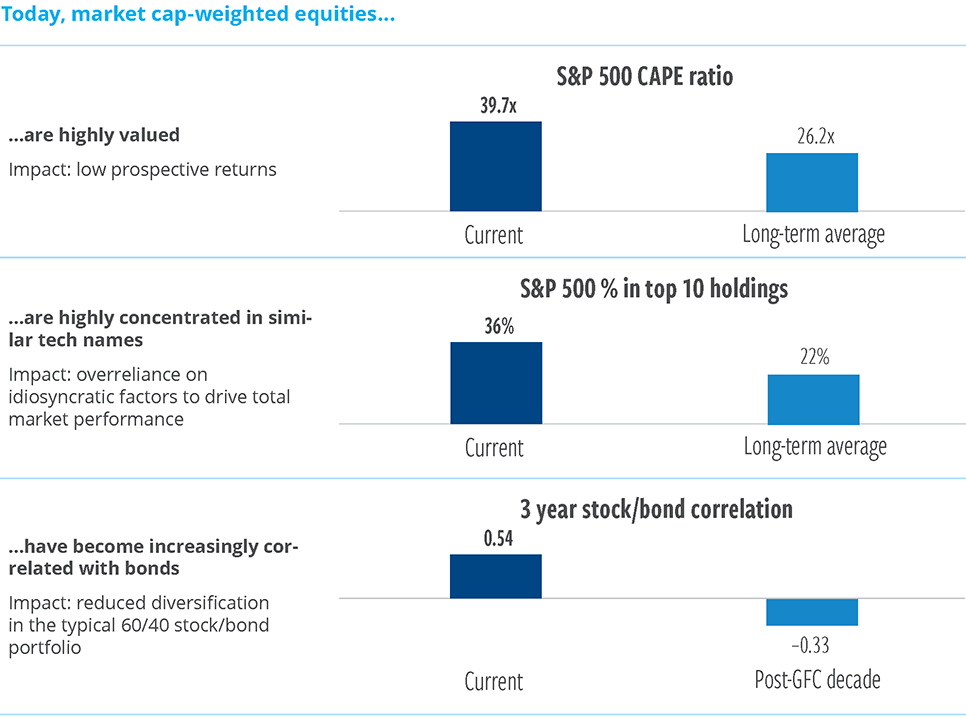
At June 30, 2026. Source: Robert Shiller Yale University, Morningstar, FactSet.
Past performance is no guarantee of future results. The cyclically adjusted price-to-earnings (CAPE) ratio is the price of the S&P 500 Index divided by its 10-year moving average of inflation- adjusted earnings. For the correlation analysis, stocks are represented by the MSCI World Index – net; bonds are represented by the ICE BofA 7-10 year U.S. Treasury Index. Post-GFC period is measured from 2012 through 2020. Long-term average is measured over 40-year periods.
Together, these conditions are leading investors to look beyond traditional asset classes for diversification, inflation sensitivity and long-term growth.
Why investors are increasingly considering real assets
Real assets are the tangible structures and raw materials that underpin the global economy. They include commercial real estate, infrastructure, natural resource equities and commodities.
EXHIBIT 3
Defining the core four real assets
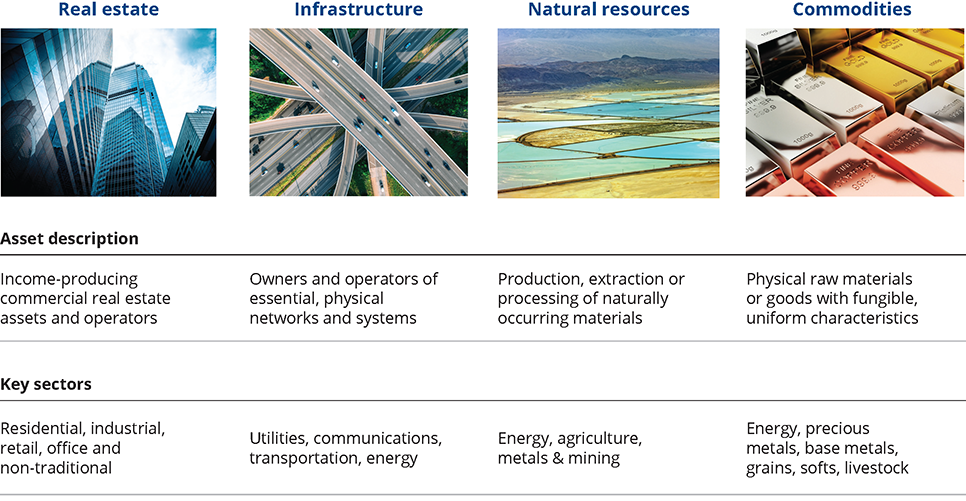
At June 30, 2026. Source: Cohen & Steers
Unlike traditional assets, real assets derive their value from physical usage, productivity, scarcity and essential economic demand.
Real assets are tangible, essential and different from traditional securities
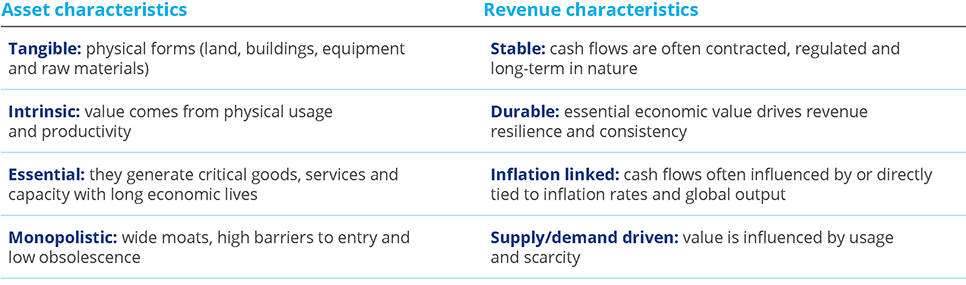
Real assets can enhance a portfolio in many ways, but they share three unifying characteristics:
1) Diversification
Real assets can respond differently to economic forces than traditional stocks and bonds. Their distinct revenue drivers and return streams can broaden portfolio diversification across market environments. Because real assets have low representation in many market cap–weighted equity indexes, investors may also have less exposure than they realize.
2) Inflation sensitivity
Many real assets cash flows are influenced by inflation, physical demand and/ or replacement costs. This can make real assets a valuable source of portfolio resilience during periods when inflation surprises pressure traditional financial assets.
3) Growth potential
Real assets are connected to durable secular themes, including AI-driven data demand, rising electricity consumption, deglobalization, demographic change, decarbonization and resource scarcity. These trends rely on the physical assets, networks, materials and energy systems that enable economic activity.
Understanding the real assets toolkit
A common misconception is that real assets represent a single asset class. In practice, they are better viewed as a toolkit of complementary investments, each offering distinct portfolio characteristics.
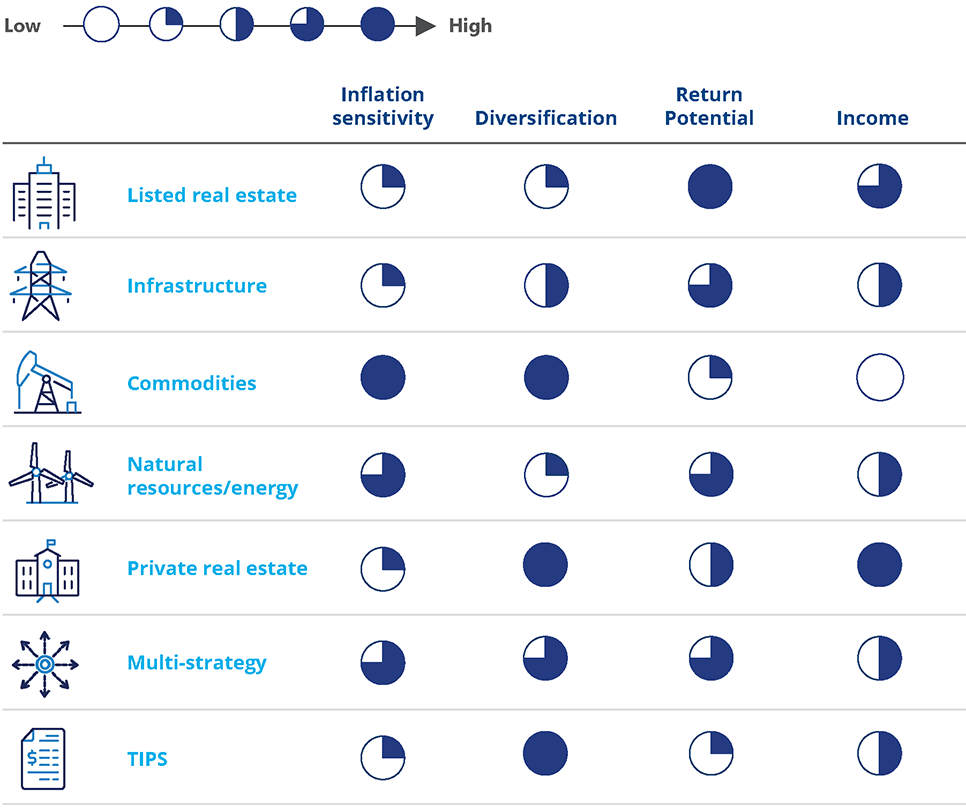
This ranges from listed real estate, which has historically outperformed other real assets but offers lower inflation sensitivity, to commodities, which have delivered lower historical returns but offered the highest inflation sensitivity among the “core four” real assets categories (Exhibit 4).
EXHIBIT 4
Each real asset category provides something different to a portfolio
Investors can combine some or all real assets based on their portfolio objective
As of June 30, 2026. Source: Cohen & Steers.
Effective implementation begins with defining the desired portfolio outcome and selecting exposures that support it
Before selecting individual strategies, investors should first determine what they are trying to achieve. The key question is “What portfolio objective am I trying to solve for?”
Seeking diversification
Investors concerned about equity concentration, changing market leadership and less reliable stock/bond diversification may consider a broad real assets allocation. Combining several real assets categories can introduce return drivers tied to physical demand, scarcity and asset-specific fundamentals.
Seeking inflation resilience
Investors focused on inflation may emphasize commodities, natural resources and energy-related investments, which have historically demonstrated stronger sensitivity to inflation surprises. Infrastructure can add inflation-linked characteristics with a different risk profile, helping diversify the allocation.
Seeking balanced outcomes
Investors seeking a mix of diversification, inflation sensitivity, income and growth may prefer a diversified allocation spanning multiple real assets categories. A broader mix can reduce dependence on any one asset class while keeping the portfolio aligned with multiple objectives.
How much real assets allocation should investors consider?
There is no single allocation appropriate for every investor. The size and composition of a real assets allocation should reflect the investor’s objectives, risk tolerance, time horizon, liquidity needs and existing allocations. Our head of multi-asset strategy, Jeff Palma, is often quoted as saying that any allocation to real assets is better than no allocation, but he also believes a meaningful allocation starts around 5%.
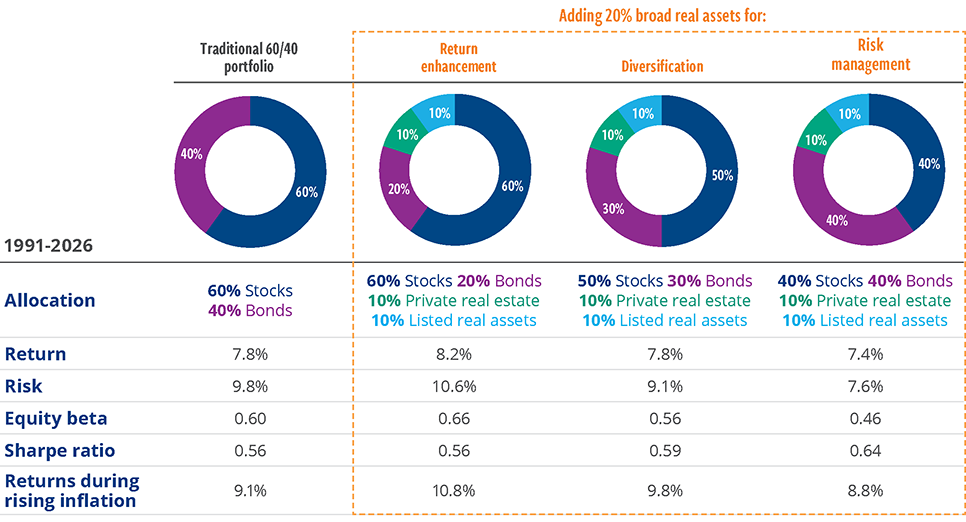
Historical analysis illustrates how a 20% broad real assets allocation could be introduced alongside stocks and bonds in different ways (Exhibit 5). The examples emphasize different goals: return enhancement, diversification or risk management. The analysis is illustrative, not a recommendation, but it demonstrates the flexibility of real assets within a broader portfolio framework.
The practical lesson is to begin with the outcome, then determine the appropriate allocation size and the investments most likely to support it. An investor prioritizing inflation sensitivity may build a different real assets mix than an investor prioritizing income or lower equity beta.
EXHIBIT 5
Real assets can help improve investor outcomes
At June 30, 2026. Source: NCREIF, Barclays, Bloomberg, Dow Jones, FTSE, S&P, LSEG Datastream, Cohen & Steers.
Past performance is no guarantee of future results. Return reflects compound annualized return. Risk reflects the annualized standard deviation of monthly returns. Equity beta measures sensitivity to the broad global equity market. Sharpe ratio measures risk-adjusted return by comparing return above the risk-free rate with volatility; a higher ratio indicates a greater return per unit of risk. Rising inflation is measured as a positive year-over-year increase in the 12-month inflation rate using the Consumer Price Index (CPI) for all urban consumers.
Choosing an approach to real assets implementation
Once investors determine the role real assets should play, the next decision is how to access them. The three approaches can be summarized as “build it, buy it or blend it.”
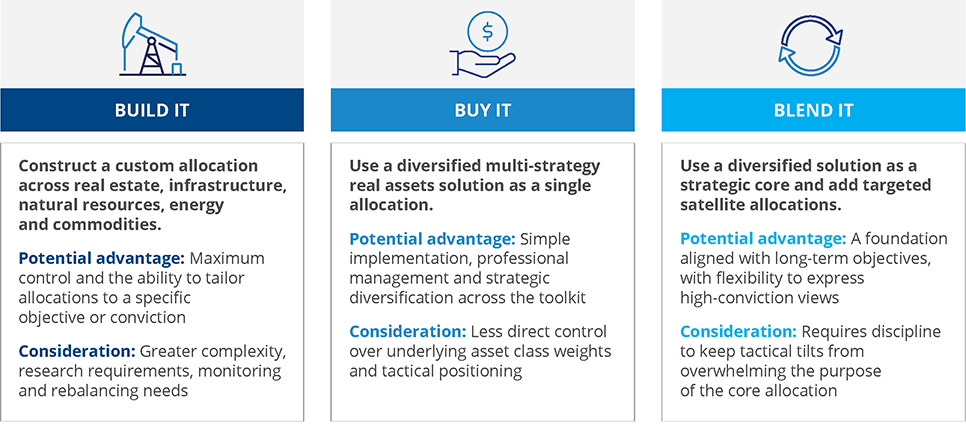
For example, an investor seeking inflation resilience could build a custom allocation emphasizing commodities and natural resources. However, removing commodity or natural resources allocations in response to a near-term tactical view could materially change the inflation characteristics of the portfolio. A diversified core with targeted satellites around it may help preserve the strategic objective while still allowing room for conviction.
Building a better portfolio with real assets
The case for real assets today extends beyond the latest market cycle. Investors are navigating evolving inflation dynamics, changing sources of economic growth, elevated market concentration and uncertainty about traditional diversification assumptions.
By starting with portfolio objectives, understanding the distinct roles of each real assets category, and selecting an implementation approach aligned with those objectives, investors can build allocations designed to broaden diversification, improve inflation resilience and participate in long-term growth opportunities.
Real assets are not a replacement for stocks and bonds. They are an additional set of tools that can help investors build portfolios for the environment ahead.
An investor cannot invest directly in an index, and index performance does not reflect the deduction of any fees, expenses or taxes. Index comparisons have limitations, as volatility and other characteristics may differ from a particular investment.
Real assets blend: 27.5% real estate, 27.5% commodities, 15% infrastructure, 15% resource equities, 10% short- duration fixed income and 5% gold. Real estate: Datastream Developed Real Estate Index through 02/28/05; FTSE EPRA/Nareit Developed Index thereafter. The Datastream Developed Real Estate Index encompasses listed real estate companies in developed markets and is compiled by LSEG Datastream. The FTSE EPRA Nareit Developed Index is an unmanaged market-weighted total return index consisting of many companies from developed markets that derive more than half of their revenue from property-related activities. Commodities: S&P GSCI Index through 07/31/98; Bloomberg Commodity Total Return Index thereafter. The S&P GSCI Index is a composite index of commodity sector returns representing an unleveraged, long-only investment in commodity futures that is broadly diversified across the spectrum of commodities. The Bloomberg Commodity Total Return Index, formerly known as the Dow Jones-UBS Commodity Index, is a broadly diversified index that tracks the commodity markets through exchange-traded futures on physical commodities, which are weighted to account for economic significance and market liquidity. Infrastructure: 50/30/20 blend of Datastream World Gas, Water & Multi-Utilities, Datastream World Pipelines and Datastream World Railroads through 07/31/08; Dow Jones Brookfield Global Infrastructure Index thereafter. The Datastream World Index Series encompasses global indexes of companies in their respective sectors (World Gas, Water & Multi-Utilities; Materials; Oil & Gas; and Pipelines) and is compiled by LSEG Datastream. The Dow Jones Brookfield Global Infrastructure Index is a float-adjusted, market-capitalization-weighted index that measures the performance of globally domiciled companies that derive more than 70% of their cash flows from infrastructure lines of business. Resource equities: 50/50 Blend of Datastream World Oil & Gas and Datastream World Basic Materials through 05/31/08; S&P Global Natural Resources Index thereafter. The Datastream World Index Series encompasses global indexes of companies in their respective sectors (Datastream World Oil & Gas and Datastream World Basic Materials) and is compiled by LSEG Datastream. The S&P Global Natural Resources Index includes 90 of the largest publicly traded companies in natural resources and commodities businesses that meet specific investability requirements, offering investors a diversified, liquid and investable equity exposure across three primary commodity-related sectors: Agribusiness, Energy and Metals & Mining. Short-duration fixed income: The ICE BofA 1–3 Year U.S. Corporate Index tracks the performance of USD-denominated investment-grade corporate debt publicly issued in the U.S. domestic market with a remaining term to maturity of less than 3 years. Gold: Spot price in USD per troy ounce. Global equities: MSCI World Index, a market-capitalization- weighted index consisting of a wide selection of stocks traded in 24 developed markets. Bonds: Bloomberg U.S. Aggregate Bond Index, a broad-based index that measures the investment-grade U.S. dollar-denominated fixed-rate taxable bond market.
Data quoted represents past performance, which is no guarantee of future results. There is no guarantee that any historical trend illustrated/referenced above will be repeated in the future, and there is no way to predict precisely when such a trend might begin. There is no guarantee that any market forecast set forth in this commentary will be realized. The views and opinions in the preceding commentary are as of the date of publication and are subject to change. Diversification does not ensure a profit, nor is it guaranteed to protect against loss. There is no guarantee that actively managed investments will outperform the broader market. This material represents an assessment of the market environment at a specific point in time and should not be relied upon as investment advice, does not constitute a recommendation to buy or sell a security or other investment, and is not intended to predict or depict performance of any investment. This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or take into account the specific objectives or circumstances of any investor. We consider the information in this presentation to be accurate, but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for investment. Please consult with your investment, tax or legal professional regarding your individual circumstances prior to investing. The views and opinions expressed are not necessarily those of any broker/dealer or its affiliates. Nothing discussed or suggested should be construed as permission to supersede or circumvent any broker/dealer policies, procedures, rules or guidelines.
Real assets risks: A real assets strategy is subject to the risk that its asset allocations may not achieve the desired risk/return characteristic, may underperform other similar investment strategies, or may cause an investor to lose money. The risks of investing in REITs are similar to those associated with direct investments in real estate securities. Property values may fall due to increasing vacancies; declining rents resulting from economic, legal, tax, political or technological developments; lack of liquidity; limited diversification; and sensitivity to certain economic factors, such as interest rate changes and market recessions. The market value of securities of natural resource companies may be affected by numerous factors, including events occurring in nature, inflationary pressures and international politics. Global infrastructure securities may be subject to regulation by various governmental authorities, such as rates charged to customers, operational or other mishaps, tariffs and changes in tax laws, regulatory policies and accounting standards. Foreign securities involve special risks, including currency fluctuation and lower liquidity. An investment in commodity-linked derivative instruments may be subject to greater volatility than investments in traditional securities, particularly if the instruments involve leverage. The value of commodity-linked derivative instruments may be affected by changes in overall market movements, commodity index volatility, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. The use of derivatives presents risks different from, and possibly greater than, the risks associated with investing directly in traditional securities. Among the risks presented are market risk, credit risk, counterparty risk, leverage risk and liquidity risk. The use of derivatives can lead to losses because of adverse movements in the price or value of the underlying asset, index or rate, which may be magnified by certain features of the derivatives. No representation or warranty is made as to the efficacy of any particular strategy or fund or the actual returns that may be achieved. Futures trading is volatile and highly leveraged and may be illiquid. Investments in commodity futures contracts and options on commodity futures contracts have a high degree of price variability and are subject to rapid and substantial price changes. Such investments could incur significant losses. There can be no assurance that the options strategy will be successful. The use of options on commodity futures contracts is to enhance risk-adjusted total returns. However, the use of options may not provide any, or may provide only partial, protection from market declines. The return performance of the commodity futures contracts may not parallel the performance of the commodities or indexes that serve as the basis for the options they buy or sell; this basis risk may reduce overall returns.
Cohen & Steers Capital Management, Inc. (Cohen & Steers) is a registered investment advisory firm that provides investment management services to corporate retirement, public and union retirement plans, endowments, foundations and mutual funds. Cohen & Steers Asia Limited is authorized and regulated by the Securities and Futures Commission of Hong Kong (ALZ367). Cohen & Steers Japan Limited is a registered financial instruments operator (investment advisory and agency business and discretionary investment management business with the Financial Services Agency of Japan and the Kanto Local Finance Bureau No. 3157) and is a member of the Japan Investment Advisers Association. Cohen & Steers UK Limited is authorized and regulated by the Financial Conduct Authority (FRN458459). Cohen & Steers Ireland Limited is regulated by the Central Bank of Ireland (No.C188319).
For recipients in the Middle East: This document is for informational purposes only. It does not constitute or form part of any marketing initiative, any offer to issue or sell, or any solicitation of any offer to subscribe or purchase, any products, strategies or other services, nor shall it or the fact of its distribution form the basis of, or be relied on in connection with, any contract resulting therefrom. In the event that the recipient of this document wishes to receive further information with regard to any products, strategies or other services, it shall specifically request the same in writing from us.