

Welcome to the Real Estate Reel from Cohen & Steers.
KEY TAKEAWAYS
- The REIT rally may have room to run: Listed real estate appears early in a multi-year recovery cycle.
- Fundamentals are improving: Cash flow growth is accelerating, supply pressures are easing, and data centers and senior housing remain supported by secular demand.
- REITs may add diversification: With equities expensive and bond correlations higher, real estate offers an alternative source of income and growth.
REITs have had a strong 2026, up 12% through September 15.
This performance has come in the face of rising rates, confirming that REITs are not simply beholden to changes in interest rates.
In light of this strong performance, the question we get from investors is, “Have we missed the rally?”
The simple answer is no.
There are several factors that argue for continued strength for listed real estate through the end of this year and into 2027.
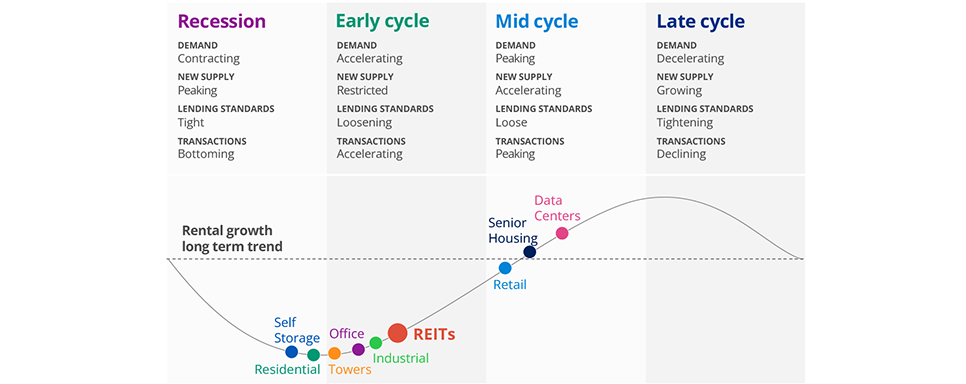
First, we believe REITs are in the early stages of a recovery cycle, as evidenced by recent reporting of second-quarter earnings.
Second, REIT sectors like senior housing and data centers continue to benefit from powerful secular growth trends.
Finally, real estate offers important diversification at a time when many traditional asset classes are less attractive.
With second-quarter earnings season completed last month, the results were encouraging.
As of June 30, 2026. Source: Cohen & Steers.
There is no guarantee that any historical trend illustrated above will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The views and opinions above are as of the date of this publication and are subject to change without notice.
The asset class is still in the early stages of what is likely to be a multi-year recovery.
Rate hikes are likely to be tempered and expected, and are more indicative of a strong economy that supports rent increases rather than a drag on real estate.
Key headwinds for core sectors like industrial and apartments, including record levels of supply are abating.
For example, the office sector, which has been plagued by the impacts of work-from-home and, earlier this year, fears of AI-driven white collar job displacement has begun to show positive momentum.
Return-to-office trends and dimming concerns of AI’s impact on employment have led to strong rental rate growth in markets like New York, San Francisco and select Sun Belt cities.
Data center leasing remains incredibly strong, even as headlines are increasingly focused on the number of local governments enacting moratoriums.
The reality is that hyperscaler capital spending continues to accelerate.
And the moratoriums, driven by public opposition over power and water, are likely to constrain future supply growth, benefiting incumbent operators in the form of lower supply leading to higher rents for existing centers in the face of such high demand.
Senior housing fundamentals were also strong in the quarter, as the demographic tailwind of seniors is being reinforced by limited new supply, which is not expected to meaningfully increase for the next several years.
Another key consideration is how investor enthusiasm for AI has overshadowed value and income-orientated sectors such as real estate.
While data centers have provided and will continue to offer exposure to AI-related growth, part of this year’s story has been the broadening of growth across the economy.
Corporate earnings have once again surprised in 2026 but as growth moderates into ’27, REIT earnings growth is expected to maintain much of its momentum.
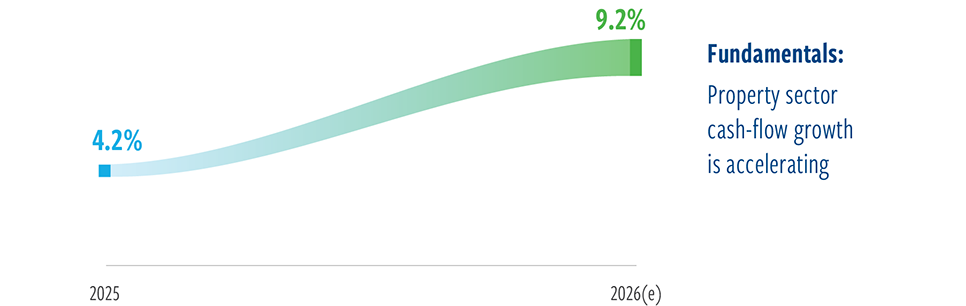
Property cash flow is accelerating
Cash flow growth (FAD)
As of June 30, 2026. Source: FactSet.
There is no guarantee that any historical trend illustrated above will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The views and opinions above are as of the date of this publication and are subject to change without notice.
In fact, property cash flow growth continues to accelerate.
As a result, the spread in earnings growth between the S&P 500 and REITs is expected to narrow, which could attract additional capital to the sector and support higher valuations.
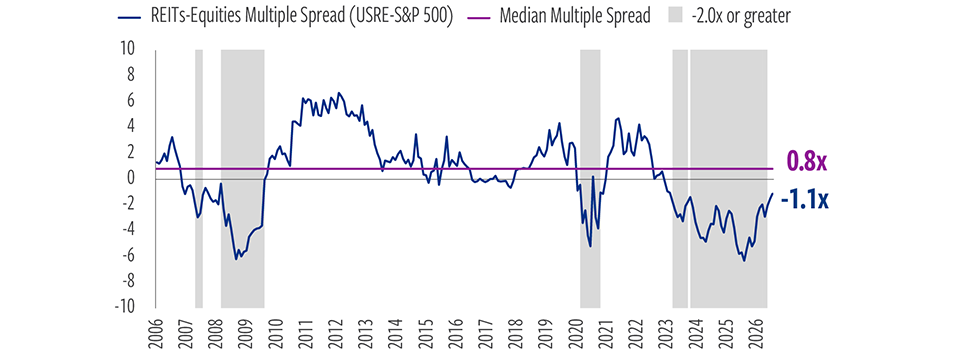
REITs are cheap relative to equities
September 2006-August 2026
At the same time, the valuation gap between REITs and the S&P remains several turns below the historical average, suggesting that REITs continue to trade at attractive relative multiples.
As of August 31, 2026. Source: UBS, Bloomberg, Cohen & Steers.
There is no guarantee that any historical trend illustrated above will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The views and opinions above are as of the date of this publication and are subject to change without notice.
REITs also offer diversification benefits.
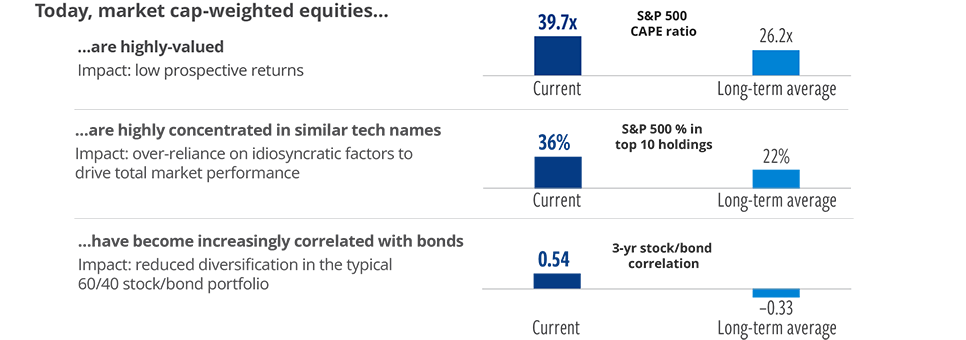
The diversifying properties of real estate are increasingly important today
As of June 30, 2026. Source: Robert Shille Yale University, Morningstar, FactSet.
Today, market-cap weighted equities are highly valued, which translates to lower expected returns.
They are high concentrated in similar technology names.
And equities have become increasingly correlated with bonds, reducing the diversification of traditional 60/40 stock bond portfolios.
We believe the real estate recovery cycle we are seeing now will be a long-lived cycle, fundamentals are strong, supply and demand continues to favor many real estate property types, and allocation alternatives, especially equities, are less attractive today.
ABOUT THE AUTHORS
Seth Laughlin, Senior Vice President, is Head of Real Estate Strategy & Research, responsible for identifying allocation opportunities in both listed and private real estate and related thematic and strategic research.
Data quoted represents past performance, which is no guarantee of future results. The information presented does not reflect the performance of any fund or account managed or serviced by Cohen & Steers, and there is no guarantee that investors will experience the type of performance reflected. There is no guarantee that any market forecast set forth in this video will be realized. There is no guarantee that any historical trend referenced herein will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The mention of specific securities is not a recommendation or solicitation to buy, sell or hold any particular security and should not be relied upon as investment advice.
This video is for informational purposes and reflects prevailing conditions and our judgment as of July 2026, which are subject to change. This material should not be relied upon as investment advice, does not constitute a recommendation to buy or sell a security or other investment and is not intended to predict or depict performance of any investment. This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or take into account the specific objectives or circumstances of any investor. We consider the information in this video to be accurate, but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for investment. Please consult with your investment, tax or legal professional regarding your individual circumstances prior to investing.
Cohen & Steers Capital Management, Inc. (Cohen & Steers) is a U.S. registered investment advisory firm that provides investment management services to corporate retirement, public and union retirement plans, U.S. endowments, foundations and mutual funds. Cohen & Steers UK Limited is authorized and regulated by the Financial Conduct Authority (FRN458459). Cohen & Steers Asia Limited is authorized and regulated by the Securities and Futures Commission of Hong Kong (ALZ367). Cohen & Steers Japan Limited is a registered financial instruments operator (investment advisory and agency business and discretionary investment management business with the Financial Services Agency of Japan and the Kanto Local Finance Bureau No. 3157) and is a member of the Japan Investment Advisers Association. Cohen & Steers Ireland Limited is regulated by the Central Bank of Ireland (No.C188319). Cohen & Steers Singapore Private Limited is a private company limited by shares in the Republic of Singapore.
M-1004414